

Digital transformation in agriculture is often sold as an instant upgrade, but a new analysis of Chinese listed agricultural companies suggests the road to digital productivity runs through a valley first. Economists Xiaorong Zhong and Changbiao Zhong of Yunnan University of Finance and Economics examined panel data on Chinese A-share listed agricultural firms from 2010 to 2022 and found that digitalization first suppresses, then boosts, total factor productivity, or TFP, the efficiency with which firms convert inputs such as labor, capital, and intermediate goods into output. In their baseline two-way fixed-effects regression, the linear coefficient of digital transformation on TFP was −0.154 (p < 0.01) and the squared coefficient was 0.036 (p < 0.01), a sign pattern that satisfies the statistical conditions for a U-shaped relationship. The estimated inflection point sits at a digitalization index value of 2.14, comfortably inside the observed range of 0 to 4.595, and formal slope tests show the curve is significantly negative at the lower bound and significantly positive at the upper bound.
The study, published in Frontiers in Sustainable Food Systems, measures digital transformation by mining the Management Discussion and Analysis sections of annual reports published on the CNINFO platform, counting keyword frequencies tied to artificial intelligence, blockchain, cloud computing, big data, and digital technology applications, then taking the natural logarithm of one plus the total frequency. TFP itself was estimated with a Cobb-Douglas production function using the Levinsohn-Petrin method as the baseline and the Olley-Pakes method as a robustness check, with output proxied by operating revenue, labor by employee counts, and capital by net fixed assets. The final unbalanced panel covers 48 firms across 13 years, or 465 firm-year observations, after excluding firms under special treatment for financial distress and observations with substantial missing data. Descriptive statistics reveal wide productivity dispersion, with TFP averaging 7.856 and a standard deviation of 0.839, and most firms still sitting at early digitalization stages, with the digital index averaging 2.381 against a maximum of 4.595.
Why does productivity fall before it rises? The authors ground the pattern in adjustment cost theory and organizational change. Early digital construction demands substantial sunk costs for hardware, system deployment, platform iteration, and staff training, and these outlays crowd out limited working capital, technical talent, and managerial bandwidth that would otherwise support routine agricultural production. Agriculture amplifies the problem: long biological growth cycles, climatic uncertainty, high asset specificity of breeding equipment, fragmented industrial chains, and limited digital literacy among frontline workers all prolong the friction-heavy phase. In the early stage, digital renovation also clashes with established agronomic routines, disrupting stable production order while immature data assets and weak cross-subject connectivity delay any efficiency payoff. Only after digital investment crosses a critical threshold do mature infrastructure, unified data standards, and organizational adaptability convert early inputs into productive stock capital, generating network synergy, reduced transaction and matching costs, and better allocation of capital, labor, and land.
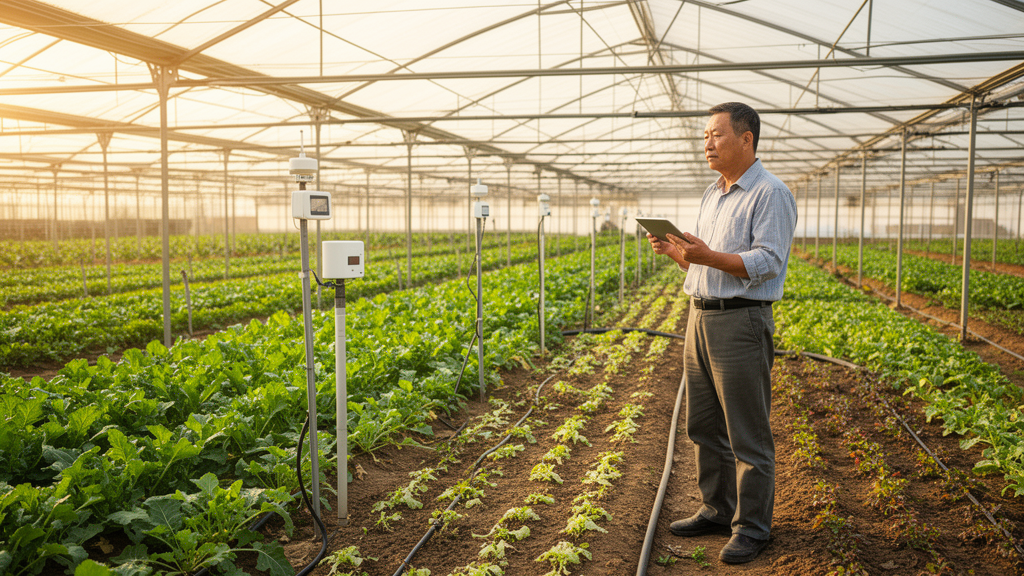
The paper’s most distinctive contribution is its identification of the transmission channel. Rather than relying on the usual soft mediators such as innovation capacity or human capital, the authors introduce the fixed-asset-to-sales ratio, defined as net fixed assets divided by operating revenue, as a sector-specific mediating variable. Their theory is an inverted-U story: in early transformation, firms pile into smart terminals, environmental monitoring modules, automated feeding systems, and digital retrofits of conventional equipment, pushing the ratio up as fixed assets expand faster than revenue. Because agricultural assets such as breeding bases and cold-chain warehouses are highly specific and hard to redeploy, this rising ratio locks up liquid capital, depresses asset turnover, and crowds out resources for research and operational upgrading, dragging TFP down. Once digitalization deepens, the relationship reverses: internet-of-things sensors, predictive analytics, and remote diagnostics revitalize existing machinery without massive new outlays, digital platforms improve credit access and asset scheduling across seasons and regions, and sharing-based business models let firms separate ownership from usage rights of fixed assets, bringing the ratio back down.
The empirical mediation test follows the nonlinear procedure of Hayes and Preacher rather than conventional stepwise methods, using bias-corrected bootstrap confidence intervals with 1,000 replications clustered at the firm level. The first-stage regression confirms an inverted-U link between digitalization and the fixed-asset-to-sales ratio, with a quadratic coefficient of −0.055 (p < 0.05) and an inflection point within the sample range. In the outcome equation, the fixed-asset-to-sales ratio carries a coefficient of −0.823 (p < 0.01), meaning heavier asset intensity per unit of revenue substantially suppresses TFP. The instantaneous indirect effect is −0.031 at low digitalization levels and 0.055 at the mean, neither statistically significant, but it rises to 0.140 at one standard deviation above the mean, where the confidence interval excludes zero and significance reaches the 5 percent level. Notably, the direct effect of digitalization on TFP is insignificant at all three levels, suggesting that within this sample the productivity benefit flows almost entirely through the asset-structure channel rather than through a direct technology boost.
Government subsidies enter the picture as a nonlinear moderator rather than a simple accelerant. Measured as total annual government subsidies divided by total assets, subsidy intensity interacts with both the linear and squared digitalization terms. The interaction coefficients are significantly positive, 2.902 for the linear interaction and 1.193 for the squared interaction, indicating that subsidies steepen the U-curve and shift the inflection point leftward, from 2.14 in the baseline to 2.06 evaluated at the mean subsidy level. The authors describe this as a turning-point-forward-shift and dividend-amplification mechanism: subsidies defray rigid investment burdens and supply patient capital that helps firms reach critical scale, but more intensive early investment also concentrates compatibility costs and organizational reengineering pressures, making the efficiency-loss phase steeper even as it ends sooner. Subsidy effectiveness is intensity-contingent. Splitting the sample at the median subsidy intensity, the low-subsidy group shows no significant nonlinear effect at all, while the high-subsidy group shows a squared coefficient of 0.050 significant at the 1 percent level. Only when support crosses a certain threshold does the U-shaped efficiency gain emerge, and the authors caution that excessively generous subsidies could in principle spur over-investment and asset misallocation.
The U-shaped pattern is not uniform across the corporate landscape. Using the nonlinear heterogeneity framework of Haans and colleagues, with joint Wald tests on the full coefficient vectors, the study finds the curve is statistically present for non-state-owned enterprises but absent for state-owned ones, with a between-group Wald p-value of 0.048. The authors attribute this to the market orientation and flexible structures of non-state firms versus the institutional inertia, multiple policy objectives, and hardware-heavy formalism that can characterize state-owned transformation. Firm size matters too: the joint Wald test yields a p-value of 0.021, and while both large and small firms display U-shapes, the estimated inflection point is 1.61 for small firms versus 2.36 for large ones, consistent with the higher adjustment costs and organizational rigidities of big companies. Across sub-sectors, the Wald test p-value is 0.039, and the nonlinear effect is detectable only for livestock and agricultural support-service firms, whose shorter production cycles and more standardized procedures ease digital adaptation. Crop-planting firms, constrained by longer cycles and stronger natural-environment limits, show no statistically identifiable nonlinear productivity response in this sample window.
The findings carry clear policy weight for China’s agricultural modernization agenda. The authors recommend establishing a tolerance mechanism for the transitional pain period, so that short-term efficiency losses are not misread as transformation failure, and shifting subsidies from hardware-oriented grants toward soft support such as organizational reform, operational optimization, and workforce training. They also argue for precisely targeted assistance to non-state-owned, small-scale, and livestock enterprises, the groups where the digitalization-TFP dividend is most demonstrably released. The distinction from manufacturing is theoretically important: while manufacturing studies often report immediate, linear productivity gains from digitalization, agricultural transformation features stage-specific cost thresholds and delayed dividend release, meaning average-effect estimates can mask the transitional losses that individual firms endure.
Important limitations temper the conclusions. The authors themselves note that despite instrumental-variable, control-function, and propensity-score matching approaches, the observational nature of the data means the results should be read as robust statistical associations rather than strict causal evidence, since unobserved time-varying factors such as managerial attitudes could still confound the estimates. The mechanism analysis focuses on fixed-asset stock structure and does not separate hardware-oriented digital investment from software-driven data-capacity building, and the subsidy analysis treats government support as an aggregate without distinguishing spending purposes. Most fundamentally, the sample consists of A-share listed agricultural firms, which are large, market-oriented leaders and cannot represent farmer cooperatives or small and medium-sized agribusinesses, the operators who make up much of the sector’s base. For the listed leaders, however, the message is unambiguous: digital dividends in agriculture are real, but they arrive only after firms and their backers are willing to finance the climb out of the productivity trough.
Subject of Research: The U-shaped effect of digital transformation on total factor productivity in Chinese listed agricultural firms
Article Title: How to overcome the productivity pains of digital transformation? The U‑shaped TFP trajectory of Chinese agricultural firms, fixed‑asset constraints and subsidy threshold effects
Article References: Zhong, X., & Zhong, C. (2026). How to overcome the productivity pains of digital transformation? The U‑shaped TFP trajectory of Chinese agricultural firms, fixed‑asset constraints and subsidy threshold effects. Frontiers in Sustainable Food Systems, 10, Article 1992915. https://doi.org/10.3389/fsufs.2026.1992915
Image Credits: AI Generated
DOI: 10.3389/fsufs.2026.1992915
Keywords: digital transformation, total factor productivity, agricultural economics, Chinese listed firms, fixed-asset-to-sales ratio, government subsidies, U-shaped relationship, mediation analysis, firm heterogeneity, sustainable food systems, overcome, productivity
Cite Scienmag News
Alan Morgan. (October 26, 2026). Chinese Farm Firms Face a Productivity Dip Before Digital Dividends Arrive. Scienmag. https://scienmag.com/chinese-farm-firms-face-a-productivity-dip-before-digital-dividends-arrive/
Alan Morgan. "Chinese Farm Firms Face a Productivity Dip Before Digital Dividends Arrive." Scienmag, 26 October 2026, https://scienmag.com/chinese-farm-firms-face-a-productivity-dip-before-digital-dividends-arrive/. Accessed 26 October 2026.
Alan Morgan. "Chinese Farm Firms Face a Productivity Dip Before Digital Dividends Arrive." Scienmag. October 26, 2026. https://scienmag.com/chinese-farm-firms-face-a-productivity-dip-before-digital-dividends-arrive/


